

Insurance claims management software helps P&C insurers connect claim intake, coverage verification, triage, damage assessment, fraud investigation, settlement, and reporting within one platform. Modern systems combine configurable workflows with AI models that analyze documents and images, estimate claim severity, identify suspicious relationships, and support straight-through decisions.
This guide explains how an AI-powered claims platform works, which web, mobile, backend, and integration components it requires, and how insurers can move from a focused FNOL automation pilot to a production system with measurable ROI. It also examines the main factors affecting insurance claims software development cost.
How Insurance Claims Management Software Automates the P&C Claims Lifecycle
P&C claims management covers the process from the initial loss notification to settlement and closure. A claim may pass through registration, coverage review, triage, investigation, damage assessment, reserving, approval, payment, and recovery. When insurers manage these stages in separate systems, employees must manually transfer information, monitor deadlines, and coordinate work across multiple teams.
Insurance claims management software connects these activities within a controlled digital workflow. It maintains a centralized claim record, assigns responsibilities, tracks status changes, and applies operational rules at each stage. This allows insurers to manage the claim as one continuous process instead of a series of disconnected tasks.
Insurance claims management software is typically an integrated platform rather than a single web or mobile application. It may include a web-based workspace for adjusters and supervisors, self-service portals or mobile apps for policyholders, and backend services responsible for workflow automation, AI processing, data storage, and integrations with policy administration, payment, and third-party systems.
Connecting the Entire Claims Lifecycle
An insurance claims management system defines how a claim moves between departments, specialists, and external service providers. Each stage has its own responsible role, required actions, completion criteria, and escalation rules.
The platform can coordinate the lifecycle as follows:
|
Claims stage |
Role of the platform |
|
Claim registration |
Creates a digital claim file and initiates the required workflow |
|
Coverage review |
Connects the reported loss with the applicable policy |
|
Triage and assignment |
Directs the claim to the appropriate processing path and responsible employee |
|
Investigation |
Coordinates tasks, evidence review, expert involvement, and communication |
|
Damage assessment |
Supports estimation and records the calculated loss |
|
Decision and settlement |
Controls approvals, documentation, payment, and notifications |
|
Closure and recovery |
Confirms completion and manages applicable recovery actions |
|
Reporting |
Provides operational, financial, and compliance data |
The claim record is updated as work progresses. Employees can see its current status, responsible person, completed actions, unresolved tasks, and upcoming deadlines without reconstructing the case from separate applications.
Using Workflow Rules and AI-Assisted Decisions
Claims workflow automation relies on configurable rules that determine what should happen when a claim enters a new stage or meets defined conditions. The system can create tasks, send reminders, enforce approval sequences, escalate overdue cases, and prevent a claim from advancing until mandatory actions are completed.
AI can support tasks involving unstructured information, pattern recognition, or prediction. Instead of making every claim decision independently, AI models can provide classifications, scores, or recommendations within a governed workflow. Operational rules then determine whether the system may continue automatically or must create a task for an authorized employee.
This separation is important. Rules control predictable requirements, while AI assists with cases that contain variable or complex data. The workflow determines when human judgment is required.
Maintaining Human Control and Accountability
A P&C platform must distinguish between routine automation, AI-assisted recommendations, and decisions requiring human authorization. Adjusters and supervisors should be able to review the information behind a recommendation, approve or reject it, and record the reason for an override.
Role-based permissions define who may change claim data, approve a settlement, release a payment, reopen a closed case, or modify a reserve. Every material action should be associated with a user, timestamp, and workflow state.
This creates a consistent operating process without removing professional oversight. Automation handles coordination, status tracking, routine tasks, and deadline management, while claims professionals focus on investigation, negotiation, and decisions requiring experience.
Improving Claims Operations Through Centralized Data
Centralized insurance claims management software gives managers real-time visibility into claim volumes, workloads, processing times, pending approvals, settlement values, and operational bottlenecks. They can identify where claims are delayed and which workflow stages require additional capacity or process changes.
The platform also creates consistent data for measuring cycle time, automation rate, adjuster productivity, claim severity, and settlement outcomes. These insights help insurers refine workflows based on actual performance rather than manual reports.
Effective claims processing software therefore provides the operational foundation for faster resolution, consistent execution, and lower administrative costs. The first detailed automation point within this lifecycle is FNOL, where the insurer converts an initial loss report into a validated and policy-linked claim record.
FNOL Automation: From Multichannel Claim Intake to Coverage Verification
First notice of loss is the first formal record of an insured event. At this stage, the insurer must identify the policy, collect the information required for the specific loss type, and determine whether the reported event can proceed to claim handling. Built into modern insurance claims management software, FNOL automation converts submissions from different channels into a standardized, validated, and policy-linked claim record.
Standardizing Multichannel FNOL Data
A digital FNOL platform uses channel-specific connectors to support claims intake automation across web forms, mobile apps, emails, call centers, broker portals, and third-party systems. Instead of preserving each submission as an isolated message, the platform maps its contents to a common FNOL data model.
Depending on the line of insurance, the standardized record may contain:
-
policyholder and claimant details;
-
policy or certificate number;
-
date, time, and location of loss;
-
insured vehicle, property, or other asset;
-
incident type and loss description;
-
parties and witnesses involved;
-
injuries or emergency services;
-
submitted documents, images, and videos.
Each field should retain its source. For example, the system must distinguish between information entered by the policyholder, supplied by a broker, imported from a telematics provider, or extracted from an attachment. This provenance helps employees resolve conflicting information without reviewing the entire submission history.
The platform also needs idempotency and duplicate controls. If a policyholder starts a claim in a mobile app and later contacts the call center about the same event, the system should connect the new information to the existing FNOL rather than create a second claim.
Validating and Completing the Loss Report
Once the information has been standardized, the system applies validation rules configured for the relevant claim type. These rules determine which fields and supporting materials are required before the FNOL can proceed.
As part of broader insurance claims automation, an automated FNOL workflow can:
-
identify missing or incorrectly formatted fields;
-
verify names, addresses, dates, and policy numbers;
-
compare the loss date with the submission date;
-
detect conflicting information across forms and attachments;
-
check for possible duplicate losses;
-
assign confidence scores to extracted values;
-
request only the missing evidence from the claimant.
Requirements should change according to the reported event. An auto collision may require vehicle and driver details, photographs, and a police report number. A property loss may require the insured address, suspected cause of damage, affected areas, and emergency repair records.
Instead of returning the complete form, the platform can generate a targeted follow-up request. If only the police report number or several damage photographs are missing, the claimant receives a secure link for submitting those specific items. The FNOL remains open and updates automatically when the requested information arrives.
Matching the FNOL to the Correct Policy
Validated loss data must then be matched with the policy that was effective when the incident occurred. This step can be complicated when a customer has multiple policies, a policy has been renewed, or endorsements changed its terms during the coverage period.
The system queries the policy administration platform using identifiers such as the policy number, customer ID, vehicle identification number, property address, or insured asset. It should retrieve the historical policy version applicable on the date of loss rather than relying only on the policy’s current state.
If an exact match cannot be found, the FNOL should enter an exception queue with a specific reason, such as:
-
policy number not found;
-
several possible policies detected;
-
reported asset not listed;
-
loss occurred outside the effective period;
-
policy data unavailable from the source system.
This prevents uncertain cases from receiving an unsupported automated result.
Automated Coverage Verification Against Policy Terms
After identifying the correct policy version, the platform performs automated coverage verification by comparing the reported event with the applicable policy terms.
First, the rules engine verifies that the policy was active on the date of loss and that the claimant, vehicle, property, or other affected asset is insured. It then checks whether the reported cause of loss and incident location fall within the applicable coverage and territory.
The system also retrieves the relevant limits, sublimits, and deductible. Policy endorsements must be included because they may have changed the original coverage conditions before the incident occurred. If an exclusion could apply, the platform records the relevant policy clause and routes the case for review.
The result should be treated as a preliminary coverage determination rather than an automatic final denial. Clear cases can proceed with the identified coverage, limits, and deductible. Ambiguous policy language, conflicting facts, unavailable documents, or possible exclusions should generate a review task that identifies the rule or policy clause responsible for the exception.
Creating a Verified Claim Record
When the required FNOL data is complete and the policy match is confirmed, the platform can generate a claim number and create the claim in the core system. The resulting record contains normalized loss data, the relevant policy version, the preliminary coverage result, unresolved exceptions, and submitted evidence.
This structured handoff is the main operational value of FNOL automation. The next stage receives a complete and verified claim record instead of an unstructured email, partially completed form, or call-center note. The claim is then ready for risk-based triage, damage assessment, and processing decisions.
AI Claims Processing for Triage, Damage Assessment, and Straight-Through Decisions
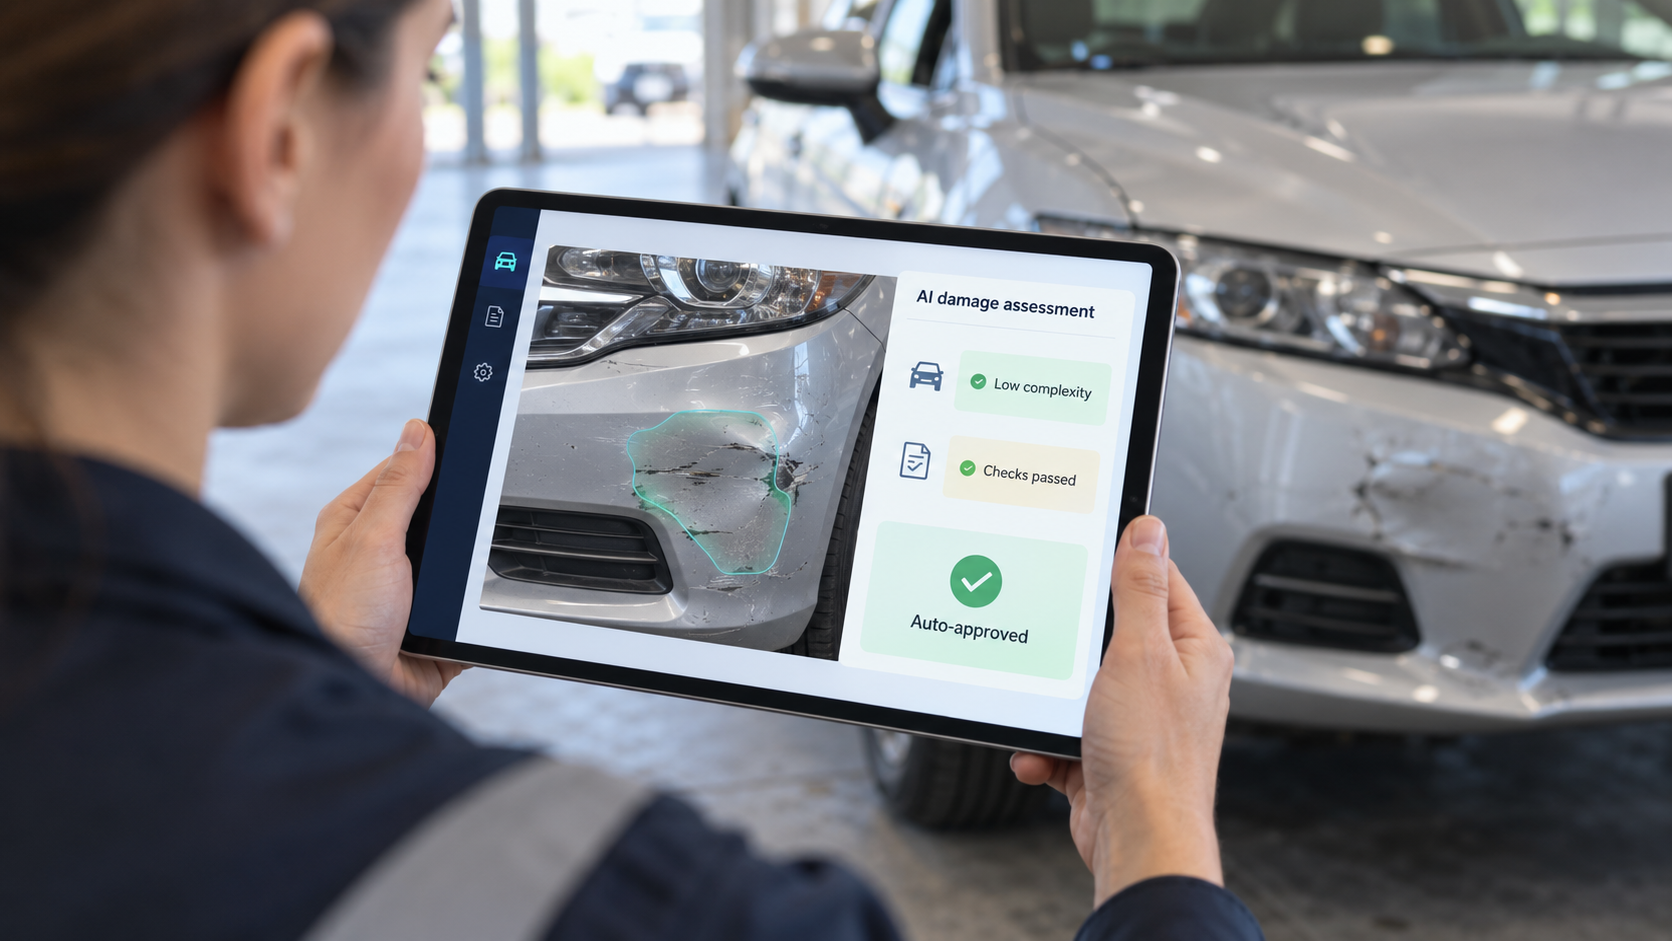
After FNOL data and preliminary coverage have been verified, insurance claims management software assigns the claim to an appropriate processing path. AI claims processing uses claim characteristics, historical outcomes, and predictive models to estimate severity, complexity, and required handling effort.
Risk-Based Claims Triage
Traditional triage relies on broad claim categories and manual review, which can place routine and complex cases in the wrong processing queues. AI claims triage evaluates multiple factors, including:
-
type and cause of loss;
-
estimated damage severity;
-
number of affected parties;
-
reported injuries;
-
geographic location;
-
catastrophe involvement;
-
litigation probability;
-
expected repair duration;
-
prior claim patterns.
Based on these factors, the model may classify a claim as low-touch, standard, complex, catastrophic, or suitable for specialist review. The system then recommends its priority, service-level target, and required expertise.
Insurers should monitor how often claims are reassigned, escalated, or require reserve changes after the initial classification. Frequent corrections may indicate that the model or its decision thresholds need adjustment. Within broader insurance claims automation, triage must produce an actionable processing route rather than only a risk score.
AI Damage Assessment for Auto and Property Claims
After triage, automated damage assessment estimates the scope and probable cost of the loss. AI damage assessment models analyze photographs, video, and asset data to identify visible damage to vehicles, buildings, equipment, or other insured property.
For an auto claim, the system may identify damaged components, determine likely repair or replacement requirements, and apply current parts and labor costs. For a property claim, it may classify affected areas and materials, calculate repair quantities, and use regional construction prices.
The estimate can be cross-checked against:
-
the claimant’s description;
-
repair shop or contractor estimates;
-
vehicle, property, or asset records;
-
weather and catastrophe data;
-
historical costs for similar losses.
The system may flag components included in a repair estimate but not visible in the submitted images or identify costs that differ significantly from comparable claims.
Each automated estimate should include a confidence level and references to the evidence used. Poor image quality, hidden damage, or an unusual asset configuration should trigger a physical inspection or expert assessment.
Supporting Initial Reserves
Damage estimates can also support the initial claim reserve. Predictive models calculate the probable financial exposure using repair costs, business interruption, bodily injury, legal involvement, recovery opportunities, and the expected claim duration.
As new information becomes available, the system can detect a material change in exposure and recommend a reserve review. This is particularly important for property, liability, and injury claims, where the final cost may not be clear during the initial assessment.
Straight-Through Claims Processing
Straight-through processing in insurance allows eligible claims to proceed from assessment to decision without manual review at every stage. A claim may qualify when coverage is confirmed, the required evidence is complete, the estimated loss falls below an authorized threshold, and no exception flags are present.
A straight-through workflow can:
-
approve the claim within a defined limit;
-
calculate the payable amount and deductible;
-
generate settlement documents;
-
initiate payment;
-
notify the policyholder;
-
refer the claim when an eligibility condition fails.
The criteria must be configurable by insurance product, jurisdiction, and claim type. A low-value windshield claim may qualify for full automated claims processing, while bodily injury, disputed liability, major property damage, or uncertain causation requires adjuster review.
Insurers should evaluate decision accuracy, reassignment rates, reserve changes, payment corrections, complaints, and reopened claims—not only the automation rate. These indicators show whether AI-powered claims processing is producing reliable decisions.
The JoinToIT team can build claims decision automation solutions that combine AI-based triage, damage assessment, reserve predictions, and configurable straight-through processing. These capabilities can be developed as part of a new claims platform or integrated into an insurer’s existing policy administration and claims management systems.
AI Fraud Detection in Insurance Claims: Risk Scoring and SIU Workflows
Fraud indicators may appear as connections between people, vehicles, properties, service providers, previous losses, and payment details. AI fraud detection in insurance claims analyzes these relationships to identify cases requiring investigation without delaying legitimate claims.
Combining Rules, Predictive Models, and Network Analysis
Traditional claims fraud detection relies on fixed rules, such as repeated claims within a short period or a loss reported soon after policy activation. These controls identify known patterns but may miss coordinated or changing schemes.
Modern insurance fraud detection software combines:
-
rules for known red flags and policy violations;
-
supervised models trained on confirmed fraud cases;
-
anomaly detection for previously unseen behavior;
-
entity resolution to identify the same person or organization across inconsistent records;
-
network analysis to detect relationships between claimants, vehicles, addresses, service providers, and bank accounts;
-
text and image analysis for inconsistencies in submitted evidence.
Entity resolution can reveal when the same participant appears under variations of a name, address, telephone number, or company registration. Network analysis can identify claims that share contact details, witnesses, repair shops, vehicles, or payment destinations.
A connection does not establish fraud, but it gives investigators context that may be missed during an individual claim review. Likewise, data inconsistencies found during FNOL validation become relevant to insurance fraud analytics only when combined with behavioral, historical, document, or network-based signals.
Creating an Explainable Fraud Risk Score
Fraud risk scoring converts detected signals into a score or risk category. The calculation may consider unusual loss timing, document anomalies, repeated participants, prior claim behavior, and relationships with suspicious entities.
The score should identify the factors that influenced it. For example, the system may explain that a claim was flagged because the repair provider appears in several connected cases, the submitted document contains unusual metadata, or the payment account is linked to another investigated claim.
This explanation helps investigators prioritize cases and prevents a numerical score from being treated as proof of wrongdoing. Insurers can configure separate SIU referral thresholds by product, claim type, financial exposure, and strength of the detected connections.
Turning Alerts Into SIU Workflows
A fraud alert becomes useful when it initiates a structured investigation. An SIU workflow connects the analytical result with the insurer’s Special Investigation Unit and creates a case containing:
-
the fraud risk score and triggering indicators;
-
relationships with other claims and entities;
-
relevant documents, images, and communications;
-
previous alerts or investigations;
-
recommended investigative actions;
-
referral deadlines and responsible employees.
The SIU investigator can accept, return, escalate, or close the referral and record the reason for the decision. Evidence requests, interviews, external database checks, investigation notes, and case status remain attached to the referral instead of being distributed across emails and spreadsheets.
Not every alert should automatically stop claim processing or payment. Depending on the evidence and financial exposure, the insurer may request another document, verify an entity, temporarily hold a payment, or open a full SIU investigation.
Improving Detection Through SIU Outcomes
Investigation outcomes provide feedback for insurance fraud detection software. Confirmed fraud, cleared alerts, inconclusive cases, and investigator overrides should be recorded separately and compared with the original model predictions.
Relevant performance indicators include:
-
false-positive rate;
-
SIU referral acceptance rate;
-
confirmed fraud rate;
-
investigation duration;
-
prevented losses;
-
investigator workload;
-
reasons for closing or overriding alerts.
A high number of alerts is not valuable if most referrals are closed without action. SIU outcomes and false-positive rates show whether detection rules and models are identifying cases worth investigating.
New data sources, rules, and model versions should be tested before they influence active claims. Access to fraud indicators must also be restricted to prevent interference with investigations or exposure of detection controls.
Integrated with insurance claims management software, AI-based fraud detection provides SIU teams with prioritized cases, connected evidence, and explainable risk indicators. Its purpose is not to label claimants automatically but to focus investigative resources on claims supported by the strongest combination of fraud signals.
Insurance Claims Software Development: Architecture, Integrations, and Data Security
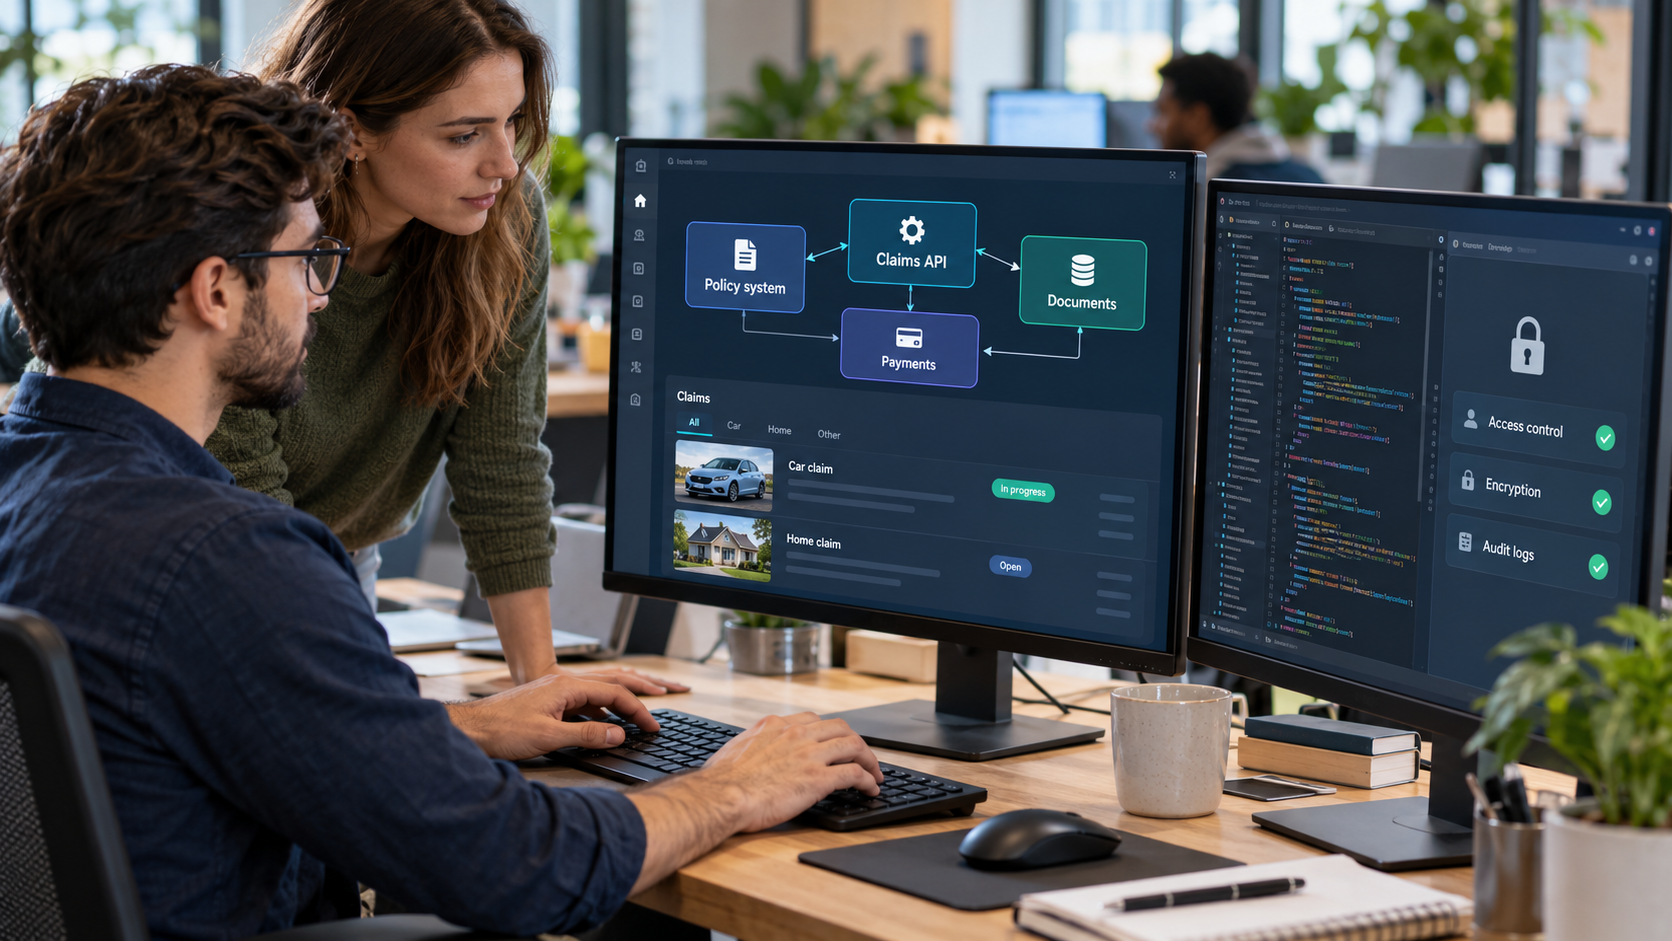
Insurance claims software development requires an architecture that can process large claim volumes, connect with legacy systems, protect sensitive data, and support products that vary by jurisdiction and line of business.
Designing a Modular Claims Platform
A modular insurance software architecture separates claim records, document storage, workflow orchestration, communications, payments, reporting, AI services, and user management. Individual components can then be updated without rebuilding the entire platform.
A typical technology stack includes:
-
web applications for internal teams and external users;
-
backend APIs for business logic and data exchange;
-
relational databases for structured claim and policy data;
-
object storage for documents, images, audio, and video;
-
event queues for asynchronous processing;
-
separate AI services for classification, prediction, and image analysis;
-
monitoring tools for application performance and errors.
An API-first architecture allows web, mobile, and partner applications to use the same backend logic. Event queues handle actions that do not need an immediate response, such as sending notifications, updating reports, or synchronizing data with external systems. This prevents a slow integration from blocking the main application.
Connecting Claims Software With Existing Systems
Most insurers need to modernize claims operations without replacing their entire technology stack. Claims system integration connects the new platform with:
-
policy administration APIs for versioned policy and coverage records;
-
billing and payment platforms for settlements, deductibles, and recoveries;
-
CRM systems for customer information and communication history;
-
document management and electronic signature services;
-
repair, estimating, and contractor platforms;
-
identity verification and external data providers;
-
accounting, reporting, and business intelligence systems.
Modern systems typically exchange data through REST or GraphQL APIs, webhooks, and event streams. Legacy platforms may require middleware, message queues, scheduled batch transfers, or custom adapters.
The integration layer should validate data, prevent duplicate transactions, retry failed requests, and record synchronization errors. It must also establish which system is the authoritative source for each data type to prevent inconsistent policy, payment, or customer records.
Isolating AI Services From Core Transactions
AI models should receive only the data required for their assigned task rather than unrestricted access to the claims database. Model inputs and outputs should pass through controlled services that enforce access policies, validate data, and record the model version used for each result.
AI services must also remain separate from transactions requiring predictable execution. If a model or external AI provider is unavailable, the platform should preserve claim data and continue core operations without waiting for that service.
Protecting Insurance Claims Data
Claims records may contain identity documents, financial information, medical details, property data, photographs, locations, and investigation materials. Essential insurance data security controls include:
-
encryption in transit and at rest;
-
role- and attribute-based access control;
-
multifactor authentication for privileged users;
-
separation of production, testing, and development environments;
-
secure storage and rotation of credentials;
-
immutable logs for sensitive actions;
-
retention and deletion policies;
-
backups and tested disaster recovery procedures;
-
monitoring for unauthorized access and unusual exports;
-
vulnerability scanning and security testing.
Authorization must be enforced across APIs, databases, file storage, administrative tools, and background services, not only in the user interface. External participants should receive access only to the records required for their tasks.
In a multi-tenant cloud claims platform, tenant isolation must extend across application services, database queries, object storage, background jobs, analytical pipelines, and reporting tools.
Compliance and Operational Resilience
Compliance requirements depend on the insurer’s markets, products, and processed data. The platform may need to support privacy regulations, financial-services requirements, regional data residency, consent management, breach reporting, and restrictions on automated decisions.
AI governance should also cover model approval, version control, bias testing, performance monitoring, explainability, and procedures for suspending a model when its outputs fall outside approved thresholds.
Operational resilience requires defined recovery objectives, monitoring of external dependencies, and procedures for integration outages. Critical functions should remain available when a partner API or analytical service is temporarily unavailable.
The JoinToIT team can provide end-to-end claims management software development, including API-first backend architecture, cloud infrastructure, secure web and mobile applications, AI service integration, legacy system adapters, and data protection controls.
Insurance Claims Management Software Cost: From FNOL Pilot to Measurable ROI
The insurance claims management software cost depends on whether an insurer is adding one automation module to an existing system or building a complete multi-line claims platform. The scope, number of integrations, condition of historical data, AI requirements, and expected claim volume have the greatest influence on the budget.
Public estimates vary considerably. A specialized claims solution with automation and analytics may cost approximately $250,000-$600,000, while a large AI-powered insurance system can exceed $1 million (ScienceSoft insurance development guide). These figures provide a market reference, but an accurate estimate requires a defined scope and assessment of the insurer’s current systems.
Insurance Claims Software Development Cost by Project Stage
A staged rollout allows an insurer to validate one use case before investing in a complete platform.
Based on public market estimates and the scope assumptions below, a staged claims software project may fall within the following ranges.
|
Project stage |
Typical scope |
Estimated cost |
Indicative timeline |
|
Discovery and technical prototype |
Process mapping, data assessment, architecture, clickable prototype, limited AI validation |
$12,000-$30,000 |
4-8 weeks |
|
FNOL automation pilot |
One claim type, one intake channel, policy lookup, data validation, review screen, basic reporting |
$40,000-$75,000 |
3-4 months |
|
Claims automation MVP |
FNOL, triage, document processing, adjuster workspace, basic integrations, user roles, analytics |
$90,000-$175,000 |
5-8 months |
|
Production claims platform |
Multiple claim types, AI-assisted decisions, payments, partner access, several core integrations |
$200,000-$450,000 |
8-14 months |
|
Enterprise multi-line platform |
Multiple products and jurisdictions, advanced AI, high availability, migration, complex legacy integrations |
$500,000-$2 million+ |
12-24+ months |
These ranges are planning estimates rather than fixed prices. A focused module connected to documented APIs may remain near the lower boundary. Replacing a legacy claims system, migrating historical records, and supporting multiple products or jurisdictions will move the project toward the upper range.
What Determines the Final Development Budget
The main cost drivers are:
-
the number of claim types and insurance products;
-
whether the project extends or replaces an existing system;
-
the amount and condition of historical data;
-
the number and complexity of integrations;
-
the use of custom models or third-party AI services;
-
required data migration and reconciliation;
-
transaction volumes and availability requirements;
-
regulatory, security, and audit requirements;
-
testing, deployment, and post-launch support.
The estimate should cover not only feature development but also data preparation, integrations, testing, cloud infrastructure, AI usage, security validation, and ongoing support.
Example 1: Starting With an FNOL Pilot
Consider a P&C insurer that receives 50,000 claims annually. Employees spend an average of eight minutes per claim transferring FNOL information into internal systems and requesting missing details.
At a loaded labor cost of $45 per hour, the annual cost of this work is approximately:
50,000 claims × 8 minutes ÷ 60 × $45 = $300,000 per year
Assume the insurer launches a $120,000 FNOL automation pilot for one high-volume claim type. If the production solution removes most of this work and requires $30,000 in annual infrastructure and support, the potential annual benefit after operating costs is approximately $270,000.
Under this simplified scenario, the initial investment could be recovered in approximately five to six months after full rollout. The actual calculation must account for the percentage of claims processed automatically and the time employees continue to spend on exceptions.
Example 2: Calculating Straight-Through Processing Savings
If 20,000 eligible claims are processed automatically and each saves $18 in handling costs, the direct annual saving is:
20,000 automated claims × $18 = $360,000 per year
This calculation should include only verified reductions in handling costs. Faster settlement, customer experience, and employee capacity can be reported as additional operational outcomes, but they should not be converted into financial benefits without supporting data.
Measuring Claims Automation ROI
Before development starts, the insurer should establish a financial baseline for the selected claim type:
-
annual claim volume;
-
average manual handling time;
-
loaded employee cost;
-
cost per processed claim;
-
external processing and vendor costs;
-
annual cost of existing systems;
-
estimated claim leakage;
-
verified fraud losses;
-
expected infrastructure and support costs.
A basic first-year claims automation ROI calculation is:
ROI = (annual financial benefit − annual operating cost − initial investment) ÷ initial investment × 100%
Financial benefits may include verified labor savings, reduced external processing costs, prevented leakage, and avoided fraud losses. The same saving must not be counted under several categories.
Operational quality indicators established for triage, straight-through processing, and fraud detection should remain guardrails. An automation project should not be considered successful if it reduces handling costs but increases incorrect payments, disputes, or manual corrections.
From FNOL Pilot to Production
A pilot should confirm:
-
Whether the solution produces sufficiently accurate results using real claim data;
-
Whether it reduces handling time or cost without creating additional corrections;
-
Whether it can operate with the insurer’s production systems and security requirements.
If the pilot meets predefined targets, the insurer can extend the solution to additional claim types, channels, and business units. The resulting performance data provides a stronger basis for estimating each subsequent release.
The JoinToIT team can help you validate an insurance claims automation use case, estimate the required integrations and infrastructure, and develop the solution from an FNOL pilot to a production-ready platform. Contact us to define the project scope, budget, timeline, and measurable ROI targets.